


What to Ask a Financial Advisor in Connecticut: 11 Questions to Ask Before Hiring One
Thinking of working with a financial advisor in Connecticut? Ask these questions to find out if you’re talking to the right person.
The questions below can get you started, and the explanations provide context for evaluating prospective advisors. Remember, if you don’t understand something, there’s nothing wrong with asking for clarification. Changing advisors can be a pain, so it’s best to get all the details right before making a decision.
If somebody gets dodgy when you ask for more details, that probably tells you everything you need to know. But if an advisor is open and honest, making a genuine effort to help you understand what your relationship might look like, that’s a good sign. The same is true of those who clearly explain how much they earn from working with you.
Summary: 11 Questions to Ask a Financial Advisor in Connecticut
Two questions to ask carefully
Are you a fiduciary with all clients at all times?
A fiduciary financial advisor is required to act in their clients' best interests within the scope of their fiduciary duty. This includes addressing conflicts of interest and providing required disclosures. But not every professional who calls themselves a financial advisor, financial planner, or financial consultant operates under the same legal obligations in every situation.
You use the word fiduciary, but is that always the case?
Some advisors may act as fiduciaries in certain circumstances and under different standards in others. To avoid confusion, ask whether the advisor acts as a fiduciary throughout your relationship and whether they receive commissions or other compensation that could create conflicts of interest.
If you're looking for a financial advisor in Connecticut, it's worth asking whether they provide advice as an independent registered investment adviser (RIA), work through a broker-dealer, or use another business model. The important thing is to understand the capacity in which they're working with you and how that affects their obligations.
How do you earn money?
Ask financial advisors how they charge clients. You can pay for financial advice in a variety of ways. Perhaps the most dangerous situation is working with somebody when you don't know how they earn money or how much they're charging you. When somebody says there are no fees, proceed with caution.
Compensation models generally fall into these categories:
Fee-only: Advisors receive compensation directly from clients through project-based fees, hourly fees, asset-management fees, or other flat fees. Fee-only advisors do not receive commissions for selling financial products. This can reduce certain conflicts of interest, although it's still important to understand all the fees you pay.
Commission: When you buy a financial product, a salesperson may earn a commission. Whether you see that commission or know how much it is depends on the product and the applicable disclosures. The potential problem is incentives: When somebody's livelihood depends on you buying a product, there may be an incentive to recommend that product over other options.
Fee-based: A fee-based advisor can earn both fees and commissions. The term is often confused with fee-only, but they're different. Ask whether the advisor receives commissions, referral compensation, or other payments in addition to the fees you pay.
When comparing Connecticut financial advisors, ask for a clear explanation of the total cost of working together. If you're paying an ongoing percentage of your investment portfolio, ask how that fee changes as your assets grow. If you're paying a flat planning fee, ask exactly what services are included.
How long have you been working directly with clients?
When it comes to your finances, experience may be important. Some newer advisors bring fresh perspectives and up-to-date knowledge, but experience can be valuable when navigating complicated financial decisions.
As you ask about experience, focus on client-facing experience with the topics you need help with. Somebody might have worked for an investment or other financial firm for a long time, but unless they were helping clients like you, their day-to-day work may have been different from what you need.
For example, if you're approaching retirement in Connecticut, you may want an advisor who has experience coordinating retirement income, Social Security, Medicare, investment withdrawals, and tax planning. If you own a small business, you may need help with cash flow, business retirement plans, and eventually transitioning out of the business.
How often will we meet to discuss my finances?
Find out what your experience as a client will look like. Do you need to proactively contact your advisor periodically, or will they reach out to you? Does the frequency of contact vary throughout your relationship, or is there a rigid system in place?
One and done? Some advisors are eager to win your business, but they disappear after you transfer money to them. If that's not what you want, listen for cues as you ask about the client experience. During your interview, ask how they communicate with clients during market volatility and whether they provide regular updates.
How much is right? Consider how much contact you want with your advisor. At the beginning of a financial planning relationship, there may be a lot of communication about your goals, financial accounts, and priorities. But what do you want after that? Would you prefer quarterly meetings, a few calls per year, or more frequent contact?
Ask how the advisor handles questions between meetings, whether email support is included, and what happens when your circumstances change.
Do you have a clean regulatory background?
This is something clients often fail to ask their advisors. In addition to asking, you should verify the information for yourself.
If you're researching a financial advisor in Connecticut, you can start with the SEC's Investment Adviser Public Disclosure website. Depending on the advisor's registration and business model, you may also need to check FINRA's BrokerCheck.
These resources can provide information about an advisor's registration, employment history, and reportable disciplinary events. Not every advisor will appear in the same database, so check the appropriate source for the type of professional you're considering.
If you find a negative mark in an advisor's history, ask what happened and decide whether you're comfortable with the explanation. A disclosure doesn't automatically tell the whole story, but you should understand it before moving forward.
What kind of experience do you have with goals like mine?
An advisor might be really smart, but if they don't work with people who have needs similar to yours, they might not be the right fit.
If you want help with retirement, look for somebody who focuses on retirement planning. If you own a business, ask whether they understand the financial decisions that come with running a business and eventually stepping away from it.
For Connecticut residents, it may also be helpful to ask how the advisor incorporates state-specific considerations into your plan. These could include Connecticut income taxes, retirement income, property-related expenses, and the tax implications of moving to another state.
You don't necessarily need someone who specializes exclusively in your exact situation, but you do want an advisor who understands the issues you're likely to encounter.
What education and certifications do you have?
Education and professional certifications can help demonstrate that an advisor has studied financial planning and committed to professional standards.
Look for a Certified Financial Planner™ (CFP®) professional if you want comprehensive financial planning. The designation requires education, an examination, relevant experience, and ongoing professional requirements.
You can learn more about the designation through the CFP Board.
Depending on your needs, other credentials may also be relevant. For example, a tax-focused credential may be useful if you're dealing with complicated tax questions.
Is this legit? Be wary of designations that sound impressive but have limited educational or experience requirements. Ask what a credential requires and how it helps the advisor serve clients.
Can you help with needs besides investment management?
Are you looking for comprehensive financial planning? Some advisors almost exclusively manage money, which may leave you wanting more.
While investment management can be valuable, it is only one part of your financial life. You may also need help with retirement income, taxes, Social Security, insurance, estate planning, cash flow, or major financial decisions.
Ask prospective advisors which services they provide directly and which require referrals to other professionals.
For example, if you're approaching retirement in Connecticut, ask whether they can help coordinate your retirement accounts, evaluate Roth conversions, plan for required minimum distributions, and assess the tax implications of your withdrawal strategy.
If you own a business, ask whether they can help you evaluate business cash flow, retirement plan options, and the role your business plays in your long-term financial independence.
What is your approach to investing and financial planning?
Ask what the actual deliverables will look like when working with an advisor.
Investment-related questions:
Do you invest in individual stocks and bonds, or do you use mutual funds and ETFs to diversify?
Do you use active or passive investments?
How often will you trade in my accounts?
Do I pay additional fees when you trade?
Where will my money be held, and how can I view my accounts?
Can I set restrictions on the investments you use?
Do you offer socially responsible or ESG investing options?
Are you independent in your investment selection, or do you offer proprietary products?
Your investments should generally be held with a reputable custodian, such as Charles Schwab or Fidelity, rather than deposited into an advisor's personal account.
Financial planning questions:
What information will you need from me?
How long does the planning process take?
What will I receive?
Will you provide investment advice as part of a planning engagement?
How much will this cost?
Do you offer one-time, ongoing, or other planning arrangements?
What happens when my circumstances change and we need to update the plan?
Which topics are included, such as taxes, cash flow, retirement, education funding, debt, real estate, investments, and insurance?
For Connecticut residents, consider asking how the advisor incorporates state and federal tax considerations into your financial plan. Your tax situation can affect decisions about retirement withdrawals, Roth conversions, charitable giving, and when to claim Social Security.
You should also understand whether the advisor prepares tax returns, coordinates with your CPA, or focuses on tax planning without filing your returns.
For asset management clients, what is your typical client size?
If you hire an advisor to manage your investments, find out how your accounts compare with those of their other clients.
This isn't about comparing yourself with other people. It's about understanding whether the advisor's business model is designed for someone with your financial circumstances.
Some advisors specialize in clients with substantial investment portfolios, while others work with younger professionals, families building wealth, or people who need financial planning but don't want ongoing investment management.
Ask whether the firm has a minimum asset requirement and whether you can receive financial planning without transferring your investments.
This can be particularly important if you're a Connecticut resident who needs retirement planning but has most of your wealth tied up in a 401(k), a business, real estate, or other assets.
Will I work with you directly, or with a junior advisor?
You may want to have a lifelong relationship with an advisor, assuming all goes well. But if you don't meet the person you'll actually work with day to day, it's hard to make a decision.
Find out how the firm operates and who you'll have access to. Will you work directly with the advisor who develops your plan, or will most of your communication be with other team members?
If you'll work with a junior advisor, ask about their background, education, experience, and planning philosophy.
You should also understand who will be responsible for your relationship if your primary advisor retires, leaves the firm, or becomes unavailable.
Two questions to ask carefully
You can ask questions that don't have a definitive answer. But a prospective advisor's response can tell you a lot about the person you're considering hiring.
Bonus Question #1 : How much will I make?
There's no way to know exactly what your investments will earn. It's a reasonable question to ask, but the honest answer is that nobody can predict future returns with certainty.
For many investors, returns will be influenced by market performance, investment costs, diversification, and the level of risk they take. If you're properly diversified, you may hold investments that don't perform well during certain periods. That's an unfortunate reality of long-term investing.
Be careful if an advisor suggests they can guarantee certain investment results, consistently beat the market, or promise unusually high returns. You may be dealing with somebody who is overconfident or willing to say anything to get a new client.
Instead, ask how the advisor plans to help you pursue your goals while managing risk.
Bonus Question #2 : What's your investment performance like?
It's understandable to ask about performance, but advisors need to use care when answering. Each client and investment strategy may be different. Past performance also doesn't tell you what your accounts will earn in the future.
An advisor may be able to discuss historical results for an investment strategy and explain how it fits your circumstances. However, the conversation should include the risks, costs, and limitations of those results.
A skilled advisor should help shift the conversation toward your goals and financial circumstances. You can control certain decisions, including your savings rate, investment allocation, and costs. You cannot control what the markets will do.
My answers
If you're considering working with In The Money Retirement Planning, here are answers to some of the questions above.
Are you a fiduciary with all clients at all times? Yes. I provide investment advisory services as a fiduciary.
How do you earn money? In The Money Retirement Planning is a fee-only financial planning firm. You can review the available services and fees on my pricing page.
How long have you been working directly with clients? I have more than 10 years of experience in the financial services industry.
How often will we meet to discuss my finances? It depends on the type of relationship and your needs. Ongoing relationships include regular planning discussions and opportunities to address questions as they arise.
What kind of experience do you have with goals like mine? I specialize in helping people prepare for retirement and make work optional as early as possible. I also work with established business owners who want to coordinate their personal finances, business cash flow, tax strategies, and long-term financial goals.
What education and certifications do you have? I am a CERTIFIED FINANCIAL PLANNER™ professional (CFP®).
Can you help with needs besides investment management? Yes. My planning services can address retirement planning, tax strategies, cash flow, investment guidance, and other financial decisions. Depending on the situation, I can also coordinate with other professionals, such as CPAs and estate planning attorneys.
What is your approach to investing and financial planning? My approach starts with understanding your goals and evaluating how your financial decisions fit together. I offer both one-time and ongoing planning arrangements, with investment management available through my full-service relationship.
For asset management clients, what is your typical client size? I work with clients whose needs and circumstances fit the services I provide. You can find information about service options and relationship minimums on my pricing page.
Will I work with you directly, or with a junior advisor? You'll work directly with me.
If you'd like to learn more about working together, book a complimentary introductory meeting. There's no obligation to move forward.
Where can you find a financial advisor in Connecticut?
If you're looking for a financial advisor in Connecticut, you can use professional directories to identify potential advisors and compare their services.
NAPFA — A directory of fee-only financial advisors.
XY Planning Network — A network of financial planners, including advisors who offer advice-only and ongoing planning services.
SEC Investment Adviser Public Disclosure — A resource for researching investment adviser firms and professionals.
Before hiring anyone, review their services, compensation, registration, and experience with situations like yours. Most importantly, make sure you understand what you're paying for and feel comfortable asking questions.
Choosing a financial advisor is about more than investment returns. The right relationship should help you make informed decisions, understand your options, and build a financial plan that supports the life you want to live.
About the Author
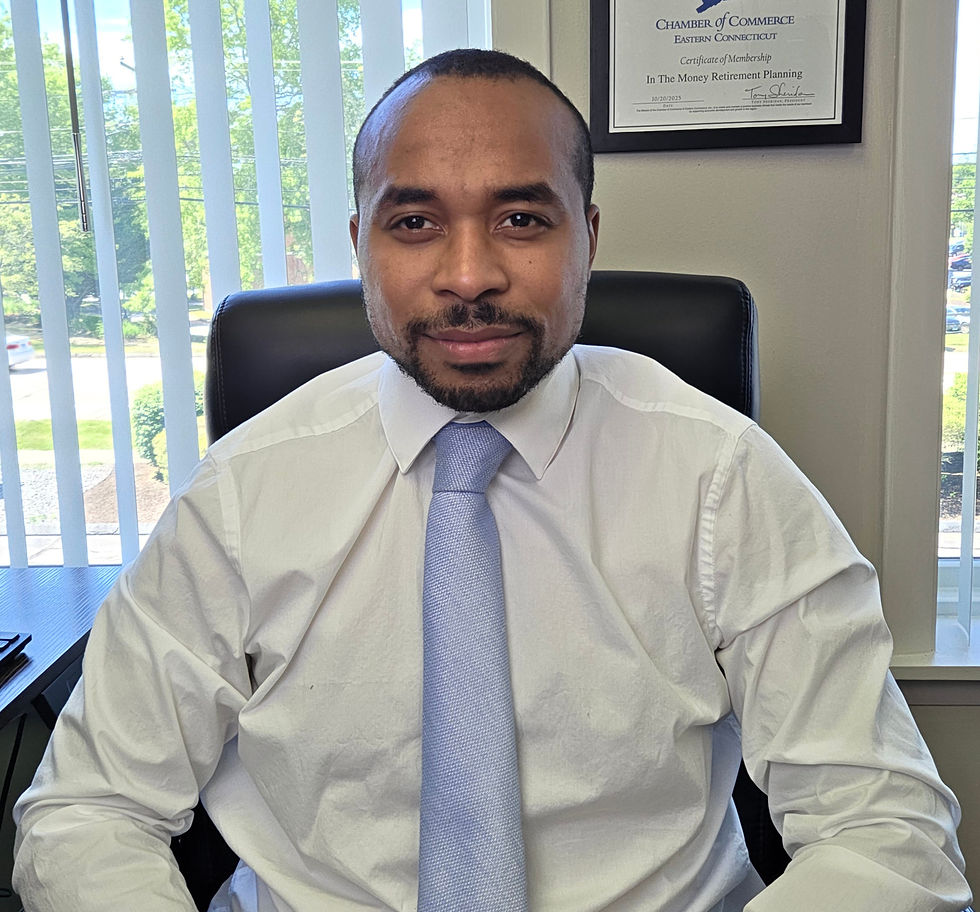
Marc Lowe, CFP® is a fee-only fiduciary advisor based in Waterford, CT, helping small business owners & families make smarter financial decisions.
The information presented in this article is the opinion of the author and does not reflect the views of any other person or entity unless specified. The information provided is believed to be reliable and obtained from reliable sources, but no liability is accepted for inaccuracies. The information provided is for informational purposes and should not be construed as advice. Advisory services offered through In The Money Retirement, an investment adviser registered with the state of Connecticut. The information linked to on third-party sites is being provided strictly as a courtesy and convenience. We make no representation as to the completeness or accuracy of information provided at these websites. When you access these websites, you are leaving our website and assume any and all responsibility and risk for use of the web sites you are visiting. The tax and estate planning information offered by the advisor is general in nature. It is provided for informational purposes only and should not be construed as legal or tax advice. Always consult an attorney or tax professional regarding your specific legal or tax situation.

Comments